
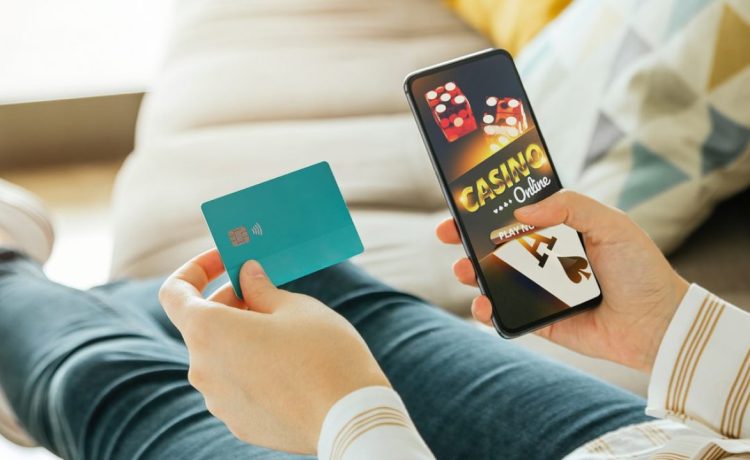
The explosive growth of the digital gambling industry has fundamentally transformed how consumers interact with casinos, sportsbooks, and online poker rooms. With a few taps on a smartphone, players can instantly fund their accounts and join a live dealer table from the comfort of their living room. The most visually friction-free way to facilitate this deposit is often pulling a credit card out of a wallet and typing in the sixteen-digit number. From the user interface perspective, it feels entirely identical to buying a pair of shoes online, ordering a meal delivery, or paying for a digital streaming subscription.
However, behind the scenes of that seamless digital transaction lies a complex and highly punitive financial trap. Credit card networks, issuing banks, and online casinos operate under a specific, rigid set of rules that treat gambling transactions very differently from standard retail purchases. Players who fund their digital casino accounts using borrowed money often discover, much too late, that their deposits are subject to a devastating combination of upfront penalties, punishing interest rates, and long-term financial consequences.
The Cash Advance Trap and Merchant Category Codes
To understand why a casino deposit triggers such severe financial penalties, you must look at how banking networks classify different types of spending. When a merchant processes a credit card transaction, the payment network assigns a Merchant Category Code to immediately identify the nature of the business. Standard retail stores, grocery chains, and restaurants all possess distinct codes that classify the transaction as a normal, everyday purchase.
Online casinos, sports betting platforms, and digital lottery sites operate under a completely different operational classification. The vast majority of major credit card issuers recognize transactions made at licensed gambling establishments as cash equivalents. This classification fundamentally alters the rules of the transaction. Because the issuing bank views the casino deposit not as buying tangible goods or services, but as literally borrowing physical cash to wager, the transaction is immediately processed as a cash advance rather than a retail purchase. This internal trigger sets off a cascade of financial penalties that fundamentally alter the true, underlying cost of your casino deposit.
Exorbitant Upfront Fees
The moment a credit card deposit clears an online casino’s payment gateway as a cash advance, the issuing bank levies an immediate, non-negotiable upfront cash advance fee. This is not a hidden charge imposed by the casino platform itself; it is a penalty written deep into the fine print of your credit card agreement.
This fee usually ranges from 3% to 5% of the cash advance amount. Alternatively, the bank may charge a flat dollar minimum, ultimately forcing the cardholder to pay whichever amount is higher. If a player deposits one thousand dollars to play blackjack on a Friday night, the bank will immediately tack an additional thirty to fifty dollars directly onto the credit card balance. This fee is non-refundable and applies to every single individual deposit made. If a player makes multiple small deposits throughout the weekend to chase losses or top off their account, they are hit with this percentage-based penalty every single time. This mechanism silently drains a player’s actual bankroll before a single bet is ever placed on the virtual felt.
The Elimination of the Grace Period
One of the primary financial benefits of using a credit card for normal retail purchases is the standardized billing grace period. When you buy groceries or book a commercial flight, the bank allows you a window of time—usually twenty-one to thirty days—to pay off the statement balance in full before any interest is actively charged to the account. This structure allows financially disciplined consumers to use credit cards as a completely free short-term loan.
Cash advances do not operate under these consumer-friendly rules. Interest on cash advances typically begins to accrue immediately without the benefit of a grace period. The moment a gambling deposit is authorized by the network, the grace period is instantly voided for that specific transaction. Interest begins compounding on a daily basis from the exact second the funds are transferred to the casino. Even if a player wins their bets, withdraws their money the very next morning, and pays off their credit card balance entirely by the end of the billing cycle, they will still be charged days or weeks worth of daily compounded interest on the original deposit amount.
Punishing Interest Rates
Compounding the severity of the immediate interest accrual is the cash advance Annual Percentage Rate. Credit cards generally utilize tiered interest rates depending on the specific type of transaction being processed. The Annual Percentage Rate for standard retail purchases might hover around a standard rate for a consumer with an excellent credit profile.
The cash advance rate is almost universally much higher. Many cards charge a higher annual percentage rate for cash advances than for regular purchases. It is not uncommon for banks to charge highly elevated interest rates on cash equivalent transactions. Because there is no grace period to shield the consumer, this exorbitant rate begins attacking the principal balance immediately. When you combine a five percent upfront fee with an elevated Annual Percentage Rate that compounds daily, the mathematical edge required to actually turn a profit at the casino becomes practically insurmountable. The built-in house edge of the casino game is completely eclipsed by the banking edge of the credit card issuer.
The Impact on Your Financial Profile
Beyond the immediate fees and interest charges, funding an online casino account with a revolving line of credit can inflict severe, long-term damage on your overall financial health. The most notable and immediate casualty of this practice is often your personal credit score.
Spiking Your Credit Utilization Ratio
A highly significant portion of a consumer’s credit score is dictated by the credit utilization ratio. This critical metric measures the amount of revolving credit currently being used against the total available credit limit extended by the banks. Because online gambling can be highly volatile, players using credit cards can quickly max out their available limits during a prolonged losing streak.
Spiking your credit utilization ratio above thirty percent will cause an immediate and steep drop in your credit score. Unlike a standard loan that is paid down predictably over time, gambling on credit creates erratic, unpredictable spikes in debt that alarm automated credit scoring models. A severely damaged credit score will impact your ability to secure favorable rates on auto loans, secure residential leases, or open new lines of credit in the future.
Red Flags for Future Lending
Furthermore, relying heavily on a credit card to gamble indicates a level of financial distress to traditional lenders. While the specific items you purchase at a grocery store do not appear on a standard credit report, the consequences of your spending habits are highly visible during manual underwriting processes.
If you attempt to secure a mortgage, underwriters will meticulously comb through your bank and credit card statements. Consistent cash advances pulled for online casinos serve as a massive red flag for risk assessment departments. Lenders view the utilization of high-interest credit for games of chance as a primary indicator of financial irresponsibility. A history of gambling deposits on a credit statement can result in a denied mortgage application, regardless of whether your overall credit score remains technically acceptable.
The Illusion of Protections and Perks
Many consumers justify using premium credit cards for their everyday expenses because of the robust rewards programs and robust fraud protections offered by the issuing networks. They assume that funneling their casino bankroll through a premium travel or cash-back card will ultimately yield thousands of points, frequent flyer miles, or statement credits.
Forfeiting Your Reward Points
This assumption is a complete illusion when applied to the online gambling sector. Because gambling deposits are coded explicitly as cash advances rather than standard retail purchases, they are entirely excluded from consumer rewards programs. If the issuer considers gambling a cash equivalent, your spending might not qualify for rewards. A player could theoretically deposit ten thousand dollars into an online sportsbook over the course of a professional football season and earn absolutely zero points, miles, or cash-back rewards for their substantial financial volume.
Limited Fraud and Chargeback Protection
Additionally, the robust chargeback protections that typically shield consumers from fraudulent retail merchants or undelivered goods rarely apply to online casinos. If a player loses their deposit at the roulette table and attempts to initiate a chargeback with their bank claiming fraud or buyer’s remorse, the bank will almost universally side with the licensed casino operator. The merchant category code explicitly alerts the bank’s dispute department that the funds were used for gambling. Financial institutions have zero tolerance for consumers attempting to utilize the chargeback system to reverse legitimate, authorized wagering losses.
Currency Conversion and Processing Markups
The financial bleeding does not necessarily stop at cash advance fees and punitive interest rates. The online gambling ecosystem is a highly globalized industry, and many popular digital casinos operate offshore or process their global payments through international financial institutions.
When a player uses a domestic credit card to fund an account held by a foreign operator, the transaction often triggers a foreign transaction fee. This is an additional percentage tacked directly onto the total deposit amount. If the digital casino operates in a different base currency, the issuing bank will also apply a currency conversion markup, offering a fundamentally less favorable exchange rate than the true global market value. When you stack a foreign transaction fee, a cash advance fee, and a heavily marked-up currency conversion rate, a player can easily lose a massive percentage of their intended deposit value before they even navigate to the virtual casino floor.
Safer Alternatives for Casino Bankrolls
To protect your financial health and ensure that your gambling budget actually goes toward placing strategic wagers, it is imperative to completely sever the connection between your credit cards and your online casino accounts. The safest and most financially responsible way to fund a digital casino account is through methods that draw directly from liquid funds you already definitively possess.
Debit cards, direct bank transfers, and reputable digital e-wallets act as a secure financial buffer. These specific payment methods process as direct electronic transfers rather than lines of credit, entirely bypassing cash advance fees, elevated interest rates, and the immediate accrual of compounding daily interest.
Using dedicated prepaid debit cards or separate, isolated checking accounts strictly allocated for entertainment funds also provides a highly necessary psychological barrier. It systematically forces players to wager only what they can actively afford to lose, entirely eliminating the dangerous temptation of chasing immediate losses with borrowed money.
Online gambling should be viewed strictly as a form of paid entertainment, requiring precise budget management and highly disciplined financial boundaries. Introducing a credit card into this environment introduces an absolutely unacceptable level of inherent risk. The brief convenience of an instant, frictionless deposit is entirely negated by the predatory structure of cash advance penalties, skyrocketing interest rates, and the potential destruction of your long-term credit profile. By understanding the hidden financial mechanics operating silently behind these digital transactions, players can make informed, responsible decisions and ensure that the only house edge they face is the mathematical probability built into the casino games themselves.